I get asked for the actual FIRE formula behind retiring at 45 with ₹1 Cr often enough that I finally wrote the whole thing down—all six parts, in the order they actually happened, not the order that makes the best headline.
Most retellings of a story like mine put the discipline first, because discipline is the part people are comfortable admiring, and they put the help I had, if they mention it at all, somewhere near the end as a footnote. I’ve decided to do the opposite in my own FIRE formula. I’m putting it second, right after the part where I decided what I was even building toward, because that’s honestly where it actually sat in the sequence, and burying it at the end is exactly the habit that makes most people miss the same part in their own lives.
Here it is, written out in full.
The FIRE Formula, Written in Full
RFF = (Picture First × Leverage × Single Asset × Location Arbitrage × Delayed Income) ^ Boring Investing
Six parts. Five of them multiply together. The sixth sits as an exponent, which is a deliberate choice, not decoration. I’ll explain why near the end, because it’s the part most formulas like this get quietly wrong.
For now, the five multiplied terms are in the order I actually lived them.
By the way, RFF statnds for the Real FIRE Formula.
Picture First: The Left Side, the Right Side, and Three Arrows in Between
I had painted my future in 2013.
It started with a question that wasn’t mine. An external facilitator running a two-day 7 Habits program at a five-star hotel in Pune asked a room full of colleagues from different departments, “If you were an artist, how would you paint the masterpiece of your life?” Nobody in the room had an answer. Neither did I. I filed it away as interesting and went back to work.
The question alone didn’t move me, not yet. I was running Adventurizants then, an adventure group I’d built from scratch inside the organization—campus grads, offsite treks, a culture of doing things that weren’t in anyone’s job description. It was the best version of corporate life I’d had, and a question about the masterpiece of my life felt, that season, like something that applied to other people.
It took two more years and a different conversation to actually find me.
My mentor had been promoted thirteen times in thirteen years. Over coffee, very quietly, he asked me something that wasn’t about career strategy at all: are you thrilled? Not do you like your job. Not are you performing well. Are you thrilled? I couldn’t answer, so he told me to sleep on it.
I thought about it for a month. In that same month, my boss made it clear, in terms I still remember precisely, that approvals I’d earned one day could simply cease to exist the next. It wasn’t dramatic. It was quiet and absolute, and the quietness of it was worse than shouting would have been. Sitting with both things together, the question and that particular kind of quiet, something clarified slowly over weeks.
The answer to “are you thrilled” was no, and the reason wasn’t one bad boss or one revoked approval. It was the distance between the work I loved—auditoriums, training rooms, the specific moment when something I said visibly shifted something in someone—and the work that was actually filling my days.
One rainy evening in 2013, I picked up an A4 sheet and some color pens.
On the left: a shouting face, unmistakably my boss. Me in the center, visibly irritated, a pile of things on the desk—the specific weight that accumulates when you’re efficient enough to finish your own job and get rewarded with someone else’s. A large question mark above all of it, because that was the truest thing I could put on the page. And underneath the job itself, something I’d lost without quite noticing: the travelling, the trekking, the time in the Himalayas that had been woven into my Adventurizants’ years and had quietly stopped somewhere I couldn’t pinpoint.
On the right: four rupee symbols, the specific abundance of income that comes from your own work rather than someone else’s approval. A figure standing in front of an audience, people with hearts drawn above their heads—the image of doing the one thing I’d always been told I was good at, speaking with clarity in a room where people were actually listening and something was actually changing.
In the middle, three arrows: Fire Boss. My Learning Company. ₹₹₹₹.
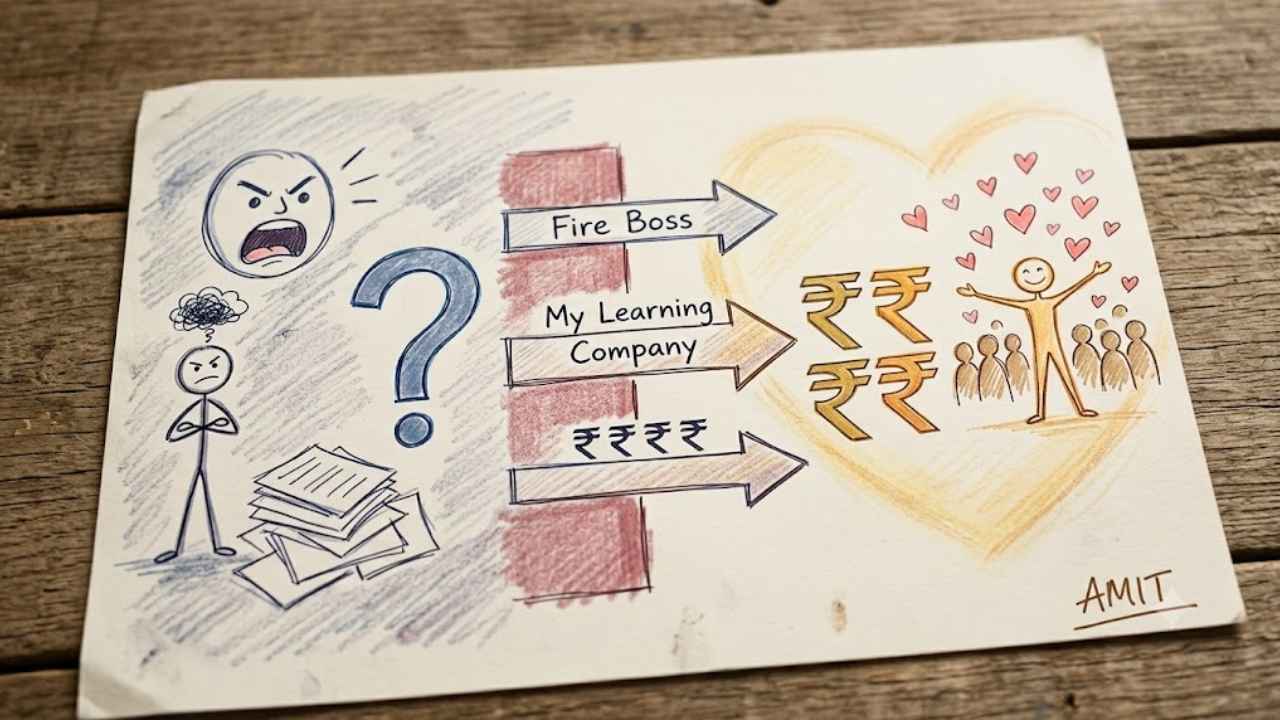
I hadn’t heard the term FIRE yet. I didn’t know it existed. I just knew the arrows pointed at something specific and controllable, not a wish.
I stuck the painting on my bedroom wall. It stayed there for two years while I figured out how to make the arrows real. The fuller version of this story, including everything that happened between the wall and the arrows becoming true, is in the book I am writing, The Picture Before the Number.
I have a friend I’ll call Aj. He’s a CXO at a mid-sized IT company, with more properties than he needs, and a salary most people would call a destination rather than a milestone. He cannot picture stopping—not because he needs the money, but because he’s never seriously drawn the right side of his own page. He visited me in Dehradun once, sat on the property, had three cups of tea in a row, said he hadn’t done that in years, and told me he was jealous of my life. Then he went back to Pune and kept running.
That’s the part a fire formula can’t fix by itself. Picture First isn’t a mindset exercise you complete once. It’s the term that makes every other term in the formula point somewhere. Without it, leverage, discipline, and patience just make you more efficient at running in a direction you never actually chose.
Leverage: Name It Before Someone Else Does
This is the part I used to put last, if I mentioned it at all, and it’s the part I now think belongs second—right after the picture, before any of the discipline.
They’re right. It was easy for me, in the specific sense they mean. I had a family property in Dehradun sitting unused for fifteen years, offered to us on the condition that we renovate it. I had one flat in Pune, already paid off, generating rental income I chose never to spend. I had a consulting and coaching practice that eventually covered our monthly costs without touching the corpus. And underneath all three, I had a corpus I never treated as the whole engine—a floor to fall back to, not a number I was drawing down to survive.
Four pieces. Not one lucky break. A structure, and I don’t think it should be erased from the story by calling it luck any more than it should be erased by insisting it was all self-made.
Here’s the pattern I’ve watched in myself and in nearly everyone I’ve coached through a version of this decision: leverage is nearly invisible to the person holding it and blindingly obvious to the person without it. The Pune flat didn’t feel like an advantage for most of the years I owned it—it felt like a stretch, an EMI that arrived whether or not the year had gone well. It only reads as leverage now, cleanly, from the outside, stripped of everything that made it a genuine risk at the time.
I see this on nearly every Clarity Call I take. Someone describes their situation as unremarkable, entirely self-built, with no advantages worth mentioning—and twenty minutes in, almost as an aside, mentions that their spouse’s income alone covers the mortgage, or that they’ve never had to support aging parents the way their siblings have, or that an old hobby has quietly been generating steady side income for years without them ever once calling it a business. None of it registers as leverage. It’s just what their life happens to contain.
I’m placing it second in this fire formula on purpose, and this is why: leverage isn’t the finishing touch that made the other four terms land a little softer. In my own sequence, it’s what made the other four possible on the timeline they actually happened on. The property deal wasn’t a bonus that arrived after the discipline—it was a precondition sitting underneath Single Asset, Location Arbitrage, and Delayed Income the entire time, whether I was naming it or not.
Put it last, and the story reads as five acts of self-made willpower with a lucky break tacked on at the end. Put it second, honestly, and the other four terms read the way they should: real, and also built on ground somebody helped clear.
Most people skip this term entirely, not out of dishonesty, but because it’s nearly impossible to see from inside your own life. It rarely feels like leverage while you’re inside it. It feels like the ordinary texture of your particular situation—the thing you’d have to explain to someone else before they’d even recognize it as an asset, because to you it was never anything but normal.
Yours might be a spouse’s stable income, a body that’s stayed healthy enough that you’ve never had to plan around a medical reality someone else is carrying, or a skill nobody’s ever asked you to charge for. Name it before someone else names it for you, in the comments, as the reason none of the rest of this counts.
Single Asset: The Discipline Was the No, Not the Flat
I bought one flat in Pune, early in my career, before the salary was big enough to make the EMI comfortable. I cleared the loan during the corporate years, and by the time I left, it was mine outright, earning roughly forty-two thousand rupees a month in rent I reinvest rather than spend.
One flat. Not two. Not a portfolio. That sounds modest, almost accidental. It wasn’t. It was the single hardest financial discipline I practiced for over a decade, and I think it mattered more to the eventual outcome than the flat itself did.
I watched a colleague, I’ll call him Rajeev, make the opposite choice, one entirely reasonable decision at a time. First flat at twenty-eight, sensible, and within budget. Second, at thirty-four, when a strong bonus year made the EMI feel easy. A third at forty, bought explicitly for his children’s future, which is the hardest version of this decision to argue against because it’s wrapped in love rather than ambition. Every individual purchase made sense on paper. Nobody buying a second property thinks of it as walking into a trap—they think of it as building an asset base.
What nobody in that sequence does, at the moment of purchase, is add the decisions together and ask what the combined structure requires going forward, regardless of what happens to their health, their role, or their appetite for the work funding all three loans at once. By fifty, Rajeev was carrying three EMIs simultaneously. His salary had grown substantially since twenty-eight—genuinely, significantly grown—and he had less real freedom than he’d had at the start, not more. He described his own five-year plan to me as “just get through it,” a phrase I don’t think he’d have recognized, at twenty-eight, as a plan at all.
The question I learned to ask myself, every time a bonus made a second property feel newly affordable, wasn’t: Can I afford it? It was: Afford it toward what?. One flat, paid off, generating money I don’t touch, was worth more to my actual freedom than three flats and three EMIs ever could have been—regardless of what the combined paper value might have looked like. The asset wasn’t the leverage here. The repeated, unglamorous decision not to expand it was.
Location Arbitrage: The House Was Never the Advantage
My wife’s uncle had a house in Dehradun that had sat unoccupied for fifteen years. It was built in 1945, a pre-independence construction that most people would find reasons to leave within a week. He offered it to us on one condition: renovate it. His thinking was practical, not sentimental. Ours was equally practical—a home in a city where costs were a fraction of what we’d been paying, in exchange for real, upfront work most people wouldn’t have wanted to take on.
Most people wouldn’t recognize this as a form of house hacking, because the term usually means something narrower—renting out a spare room, offsetting a mortgage with a tenant. What we did with an old, unoccupied ancestral property wears a different outfit, but the mechanism is identical: treating housing cost as a genuinely negotiable variable instead of a fixed one you simply pay because that’s what everyone pays.
Most families never run this calculation on their own version of it, because the word “family” attaches an emotional weight that makes evaluating the asset financially feel like a betrayal. I coached a man whose family owned a modest ancestral property outside Nagpur, visited once a year for a wedding, and otherwise sitting there generating nothing. He’d never once considered it relevant to his own planning, because in his mind it belonged to a different category than his investments entirely. When I asked what it was worth, he didn’t know.
When I asked what it would take to rent it out or sell his share, he realized he’d never asked his three siblings directly in twenty years because the property had always felt like the kind of thing you inherit and hold, not the kind of thing you actively manage. He finally had that conversation six months later. It didn’t resolve neatly—one sibling wanted to sell, two wanted to keep it—but he told me afterward that twenty years of not knowing had cost him more than the awkward six-month negotiation ever did.
I want to be honest about the part of my own version that wasn’t generosity at all. The renovation cost real money and real time. The house required us to give up comforts we’d gotten used to—wiring that had to be redone, an entire adjustment period where it felt more like a decision we were still testing than a lucky break we’d been handed. I found it clarifying eventually. Clarifying is not the same word as easy, and collapsing the two is exactly what makes people miss their own version of this when it’s sitting in front of them, filed under sentimental instead of usable.
The leverage here wasn’t free housing. It was being willing to do real, unglamorous work on a complicated asset when the easier, more familiar path was renting something new and clean in a city we already knew.
Delayed Income: Leaving Before the Income Was Ready
I left corporate with a corpus, a flat generating rental income, and the intention to build a coaching and consulting practice. I did not leave with the practice already built. The first year of income was uneven—some months fine, some months genuinely uncomfortable, the kind where you check the account more often than you’d like to admit.
Most FIRE plans assume the replacement income exists before you go. Mine didn’t. What I had, without a name for it yet, was the early, uncertain shape of what’s called Coast FIRE—a corpus large enough that, left alone to compound, it eventually reaches a full number on its own, while some form of current income, however modest, covers today’s expenses so the corpus never has to be touched. My corpus wasn’t the engine. It was the floor. The consulting income was the second leg, doing the specific job of covering today’s cost of living so the corpus didn’t have to be sized for full self-sufficiency in the first place.
I coached a woman I’ll call Kavita through the confusion this term usually causes. She’d built a genuinely healthy corpus over a long, disciplined career in senior marketing roles—by conventional standards, more than enough for most people’s version of comfortable.
But she’d only ever considered two options: stay in a role that had stopped fitting her years earlier or leave completely and lean on the corpus alone, which, run through the stricter pure-withdrawal math, made even her strong number feel not quite enough yet. One more year. Then another. She could recite her exact corpus, her exact withdrawal rate, and the exact buffer the conservative calculators told her to add. What she couldn’t describe, when I asked, was a single specific Tuesday in the life all that math was supposedly protecting.
She had never considered the middle structure, because nobody had described it to her as a legitimate option rather than a consolation prize. When we worked through what a modest bridge income might look like—ten or twelve hours a week of consulting in her own specialty—the calculation changed entirely. She didn’t need a bigger number. She needed a smaller second leg standing next to the one she already had. It let her leave two years earlier than the pure-withdrawal math alone would have ever justified.
The discomfort of that first uneven year, for both of us, wasn’t a sign the plan was wrong. It was the actual cost of building the second leg instead of skipping straight to a corpus large enough to need no second leg at all.
Boring Investing: The Exponent, Not a Sixth Term
Everything above is a decision you make once, or a handful of times, at specific forks. Boring Investing is the only term in this formula that has to survive every single day after the other five are already in place, which is exactly why it sits as an exponent instead of another multiplied term. It doesn’t add to the formula. It determines whether everything else compounds or gets quietly erased.
I’ve written the fuller version of this elsewhere, so I’ll keep it to the shape of it here: a friend I’ll call Akash watched his portfolio fall more than 30% in a month in 2020, panicked, took advice from a finfluencer who used the fear to sell him a more aggressive plan and a small crypto position, and a year later had nothing to show for the switch except more things to track.
Separately, a man I’ll call Deepak had been in the same fund for ten years, quietly compounding, until a single comment at a family gathering—someone else getting similar results in less time—sent him home excited and anxious in the same breath and eventually out of a plan that had been working the entire time.
Neither of them broke any of the first five terms. Akash had arguably already done Picture First, Single Asset, and Delayed Income correctly. What broke was the exponent—the daily, undramatic discipline of not touching a plan that was already working, because a bad month or a stray sentence made it feel, briefly, like new information. Raise a good formula to a fractional exponent, and the whole thing shrinks. That’s what an unmanaged Boring Investing term does to the rest of the fire formula above it.
Why the Order Matters More Than the List
Most people who try to reverse-engineer a fire formula like this reach for the same four terms—an asset, a location decision, an income bridge, and a disciplined portfolio—and treat them as a checklist, in whatever order feels most flattering to tell. Leverage almost never makes the list at all, and when it does, it shows up last, as a caveat, after the discipline has already taken its bow.
I don’t think that ordering is dishonest so much as instinctive. It’s more comfortable to lead with what you built and mention what you were given as a footnote. But it gets the actual mechanism backward. In my own life, the leverage came before most of the discipline had anywhere to apply itself. The property deal existed before the single-asset restraint had fifteen years to compound. Naming it second isn’t generosity toward the people who’ll say it was easy.
It’s just a more accurate description of how this fire formula actually works, and I think accuracy here does something useful: it turns “Was it fair that you had help?” into the only question that’s actually yours to answer, which is what shape the help in your own life is currently taking, unnamed.
What Your Own FIRE Formula Might Look Like?
Six terms: a picture worth pointing five decisions at, a form of leverage you may not have named yet, a discipline that’s mostly a repeated no, a housing decision you’ve filed under sentimental instead of usable, an income bridge nobody told you was a legitimate middle option, and a daily habit of not touching what’s already working.
Your own fire formula doesn’t tell you what your numbers are. It tells you which six questions are worth asking honestly, in this order, before you try to answer any of them. If you want to actually build your own version—your real numbers next to your real picture, and a clear name for whichever of these six you’ve been avoiding—that’s precisely the ninety-minute conversation Disha is built to have, with your actual corpus and your actual Tuesday in the same room instead of guessed at separately.